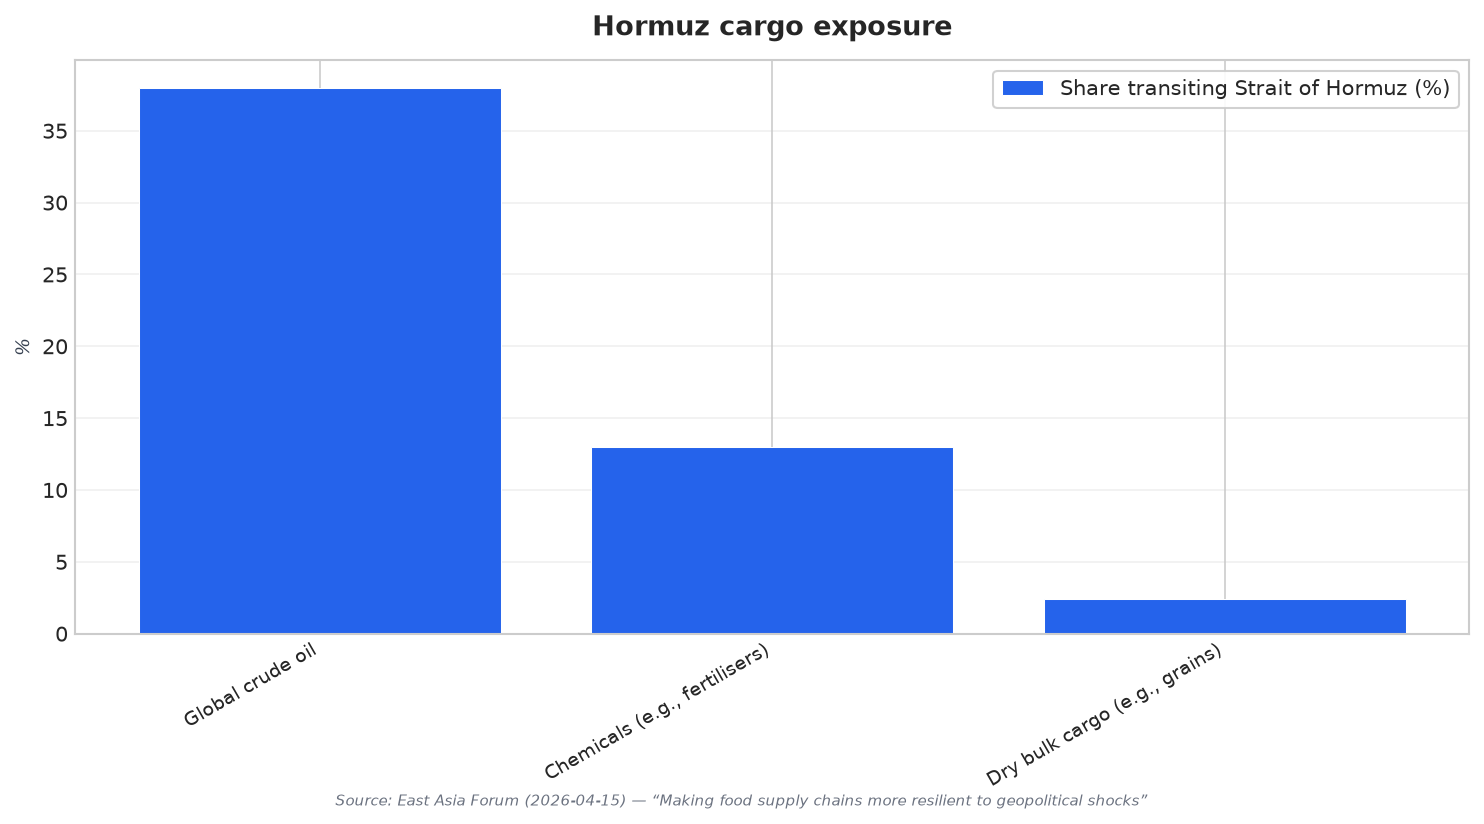
The Strait of Hormuz disruption has often been framed as an energy event, but the shock is also a direct test of food supply-chain continuity. The corridor carries around 38% of global crude oil, 13% of chemicals such as fertilisers, and 2.4% of dry bulk cargo such as grains. When a chokepoint like this destabilises, higher input costs, longer lead times, and rising risk premiums can spill into food processing, logistics, and consumer goods. UN reporting also underlined why the pressure travels fast: energy underpins farm machinery and transport, and fertilisers, particularly nitrogen-based products linked to natural gas, are critical for crop yields. The result is a multi-link disruption that goes well beyond shipping schedules.
In the GCC, the starting position is stronger than it was a decade ago, but the baseline exposure remains structural. The region imports more than 85% of its food, including virtually all rice consumption and more than 90% of cereals. At the same time, governments have been expanding strategic reserves, diversifying trade relationships, investing in domestic production, and building logistics infrastructure described as among the strongest in emerging markets. Local output has increased meaningfully in dairy, poultry, and some fresh produce. Yet the import platform is large and still growing: regional food consumption is projected to rise from 50.9 million metric tons in 2024 to 55.5 million metric tons by 2029, according to Alpen Capital. That trajectory raises the cost of getting resilience wrong.
What the Stress Test Exposed: Concentration and “Shock Entry”
One key lesson is that resilience is not only about having stock; it is also about where the system is most likely to absorb the first hit. A system-dynamics “Hormuz pressure test” model separates direct disruption from scarcity-driven trade squeeze, household access pressure, and delayed production risk. It illustrates how countries near the corridor can face high direct exposure, while geographically distant countries can still be pulled in when limited stocks and weak buffers leave little capacity to absorb even a smaller external shock. The same logic applies within food categories. While top-level supplier concentration across the GCC can look manageable, the category picture is sharper: in 2024, the top three supplying countries together accounted for less than 30% of agri-food and seafood imports, but milled rice, the region’s largest import line, was mostly (more than 90%) sourced from only two supplying countries.
The Hormuz episode also clarified why a GCC food security strategy cannot be built solely around procurement. A disruption in a critical trade corridor can ripple through manufacturing, aviation, insurance, and global logistics, with food affected via fertiliser, fuel, and transport costs. Analysts describing the GCC context highlighted three simultaneous pressure points: sourcing disruption, supply-chain friction, and fertiliser tightness, which reinforce each other and change the operating model for distributors, retailers, and regulators. UN guidance during the disruption pointed to immediate actions such as avoiding trade restrictions, supporting vulnerable households through social protection, and ensuring liquidity for farmers through credit lines and import financing. Longer-term, it argued for diversifying energy sources, strengthening infrastructure, and reducing reliance on chokepoints like Hormuz.
The most practical takeaway is that resilience has two dimensions: the ability to absorb disruption and the capacity to adapt once buffers start to erode. Work on supply-chain resilience profiles framed “Resilience Champions” as those with strategic inventories, financial slack, and the organisational ability to reconfigure routes and renegotiate contracts quickly, compared with “Glass Houses” that lack both absorption and adaptation. For GCC governments, the Hormuz shock reinforced that the right target is not simply bigger stockpiles. It is a portfolio approach: category-by-category concentration checks, reserve and logistics planning aligned to projected demand growth through 2029, and policy tools that keep trade and financing channels functional when uncertainty spreads beyond commodities.
Why did the Hormuz shock matter for food supply chains, not just energy?
How import-dependent is the GCC food system, according to the sources?
What does supplier concentration look like for GCC food imports?
What did the Hormuz “pressure test” model show about how shocks spread?
What should a GCC food security strategy prioritise after Hormuz?