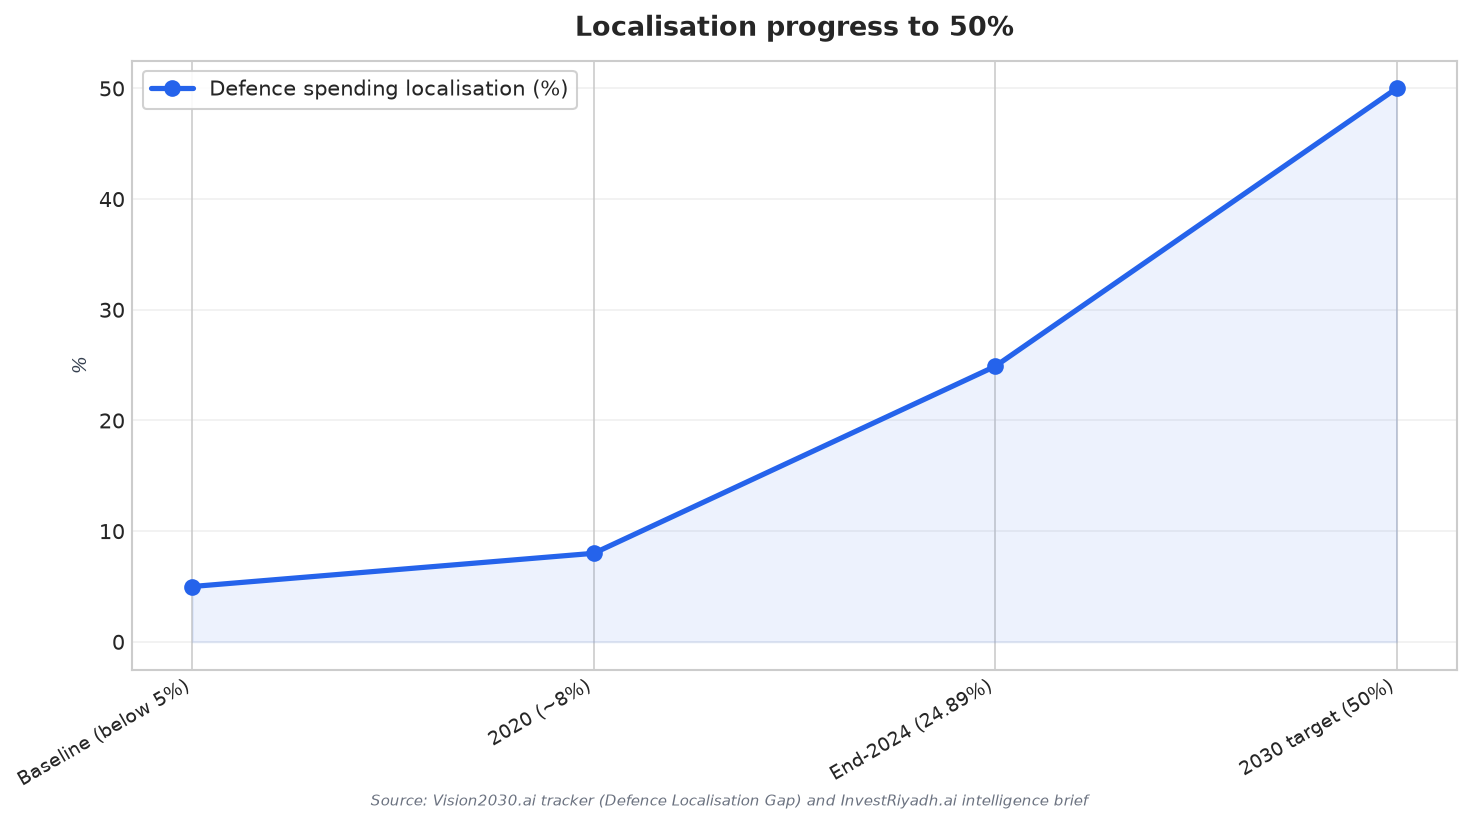
Saudi Arabia’s localisation push is no longer framed as a distant target. Sources describe it as a procurement reality that is changing how primes allocate work packages, where they build capacity, and which supplier tiers can qualify for contracts. The Vision 2030 KPI is to localise 50% of military spending by 2030, starting from a baseline where domestic defence industrial content was estimated at below 5%. Progress has been material: localisation reached 24.89% at end-2024 on GAMI’s published measure. That leaves a large gap to close, and it also creates immediate demand for suppliers who can deliver parts, services, and industrial support that count toward localisation metrics.
Budget gravity makes this shift investable. Different sources cite different definitions, but they consistently point to large-scale spending. One report cites Ministry of Finance figures estimating military expenditure at USD 63.7 billion in 2025, described as a 1.1% increase over 2024. A separate country commercial guide cites the 2025 budget and states Saudi Arabia will allocate $72.5 billion in 2025, or about 21.2% of its total budget, to defense of the Kingdom and its sovereignty. Another source, citing SIPRI via AGBI, reports Saudi Arabia spent $83 billion on defence in 2025, up 3.5% year on year, equivalent to 6.5% of GDP and about 3% of global military expenditure. For industrial suppliers, the implication is straightforward: localisation mandates can redirect meaningful workshare into Saudi-based production and services.
Where the Supply Chain Opens First: MRO, Sustainment, and Certified Parts
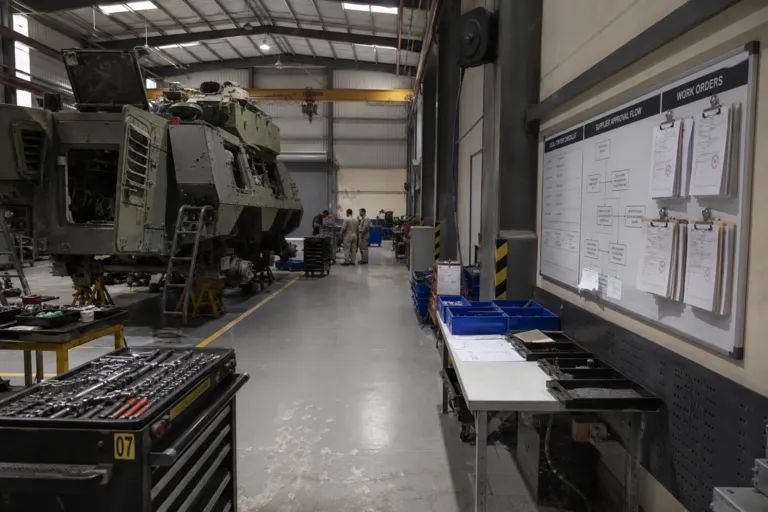
Early localisation gains are not only about manufacturing complete platforms. The Vision 2030 tracker notes that if localisation includes MRO, sustainment, and through-life support services, the achievable percentage rises significantly, because existing fleets require constant maintenance and those contracts can be transferred to Saudi-based entities, including joint ventures. The same tracker describes a pragmatic focus on maintenance, ammunition, armoured vehicles, and electronics where localisation can be achieved on shorter timelines. This is where supplier ecosystems matter: test and calibration services, repair capability, consumables, sub-assemblies, and quality certification that primes can trust. In practice, industrial suppliers that can document compliance, deliver repeatable quality, and support through-life performance can become the fastest route for OEMs to raise local-content totals.
Institutions and policy mechanisms are explicitly designed to pull suppliers into the ecosystem. Sources highlight SAMI and GAMI as core pillars, alongside a growing network of defence joint ventures. The tracker states joint ventures with Lockheed Martin, Boeing, BAE Systems, and Raytheon have created local assembly and MRO capabilities, and that GAMI’s licensing framework has attracted over 100 domestic and international companies to the Saudi defence ecosystem. A U.S. government commercial guide adds that a supply chain localization program identified more than 70 investment opportunities. It also lists demand across ground and air equipment, naval and air defense capabilities, cybersecurity, C4ISR equipment, UAV capability and Counter-UAS, aircraft engines, tactical communications systems, and MRO capabilities. For suppliers, this is the operating map: align offers to these categories, and structure delivery so primes can book it as localisation.
For industrial suppliers trying to position for Saudi defense localization, the central question is not whether the market is active, but where localisation is measurable and contractable. The tracker warns that high-value platforms such as fighter aircraft, advanced missile systems, and naval vessels require decades of capability development that cannot be compressed into a single programme cycle. That reality pushes near-term opportunity toward supplier-ready work packages that can scale quickly—licensed production support, certified parts, and sustainment capacity embedded in Saudi-based entities. Offset requirements on new procurement contracts mandate minimum local-content percentages, and sources describe localisation requirements exceeding 50% on individual planned procurements. This is why supplier readiness—quality systems, documentation, and local operating structures—can be the difference between being a vendor and being counted.
What is Saudi Arabia’s defence localisation target under Vision 2030?
How far has localisation progressed so far?
Which segments are opening first for industrial suppliers?
What signals show sustained demand for localisation workshare?
How does the Saudi defense localization ecosystem bring suppliers in?