Listing season in the Gulf has taken on a different tone in 2026. It is more selective, more sensitive to timing, and more focused on readiness. In the first half of 2026, seven IPOs across the GCC raised $1.19 billion as issuers navigated market volatility, according to Khaleej Times citing S&P Global Market Intelligence. That same report noted that Gulf IPO activity was in flux in Q2 as war dragged on, but the presence of a prospective pipeline supported confidence in the region’s long-term economic and capital-market outlook. In other words, the 2026 story is not only about what listed. It is also about what is preparing to list.
The Gulf’s data points also show a market learning to manage episodic windows. In Q2 2026, three GCC IPOs were completed, raising nearly $750 million, while other transactions paused. Saudi-based Mutlaq Al-Ghowairi Contracting Co. withdrew its planned IPO after consultations with advisers, and AlDyar AlArabiya Real Estate Development Co. halted its plans amid weaker sentiment, Khaleej Times reported. This mix of execution and delay can be read as a maturity signal. It shows issuers and advisers making go-or-no-go decisions based on conditions rather than forcing deals through, and it underscores that volatility can coexist with an active, investable pipeline.
What the Pipeline Says About Capital-Market Maturity
Forward indicators matter because they reflect intent, preparation, and confidence. Khaleej Times described potential listings that include Saudi Arabia’s Health Water Bottling Co. Ltd., delivery platform Ninja, and Etihad Salam Telecom Co. It also cited reported interest from Qatar-based Apex Health and Kuwaiti online retailer Boutiqaat. Separately, The National reported expectations that Abu Dhabi Securities Exchange and Dubai Financial Market were expecting nine to 12 IPOs in the first half of 2026, with focus areas including real estate, aviation, tech/digital platforms, logistics, utilities, and hospitality. Even when some names remain unconfirmed, the breadth of sectors and countries suggests the region is building a more continuous listing culture.
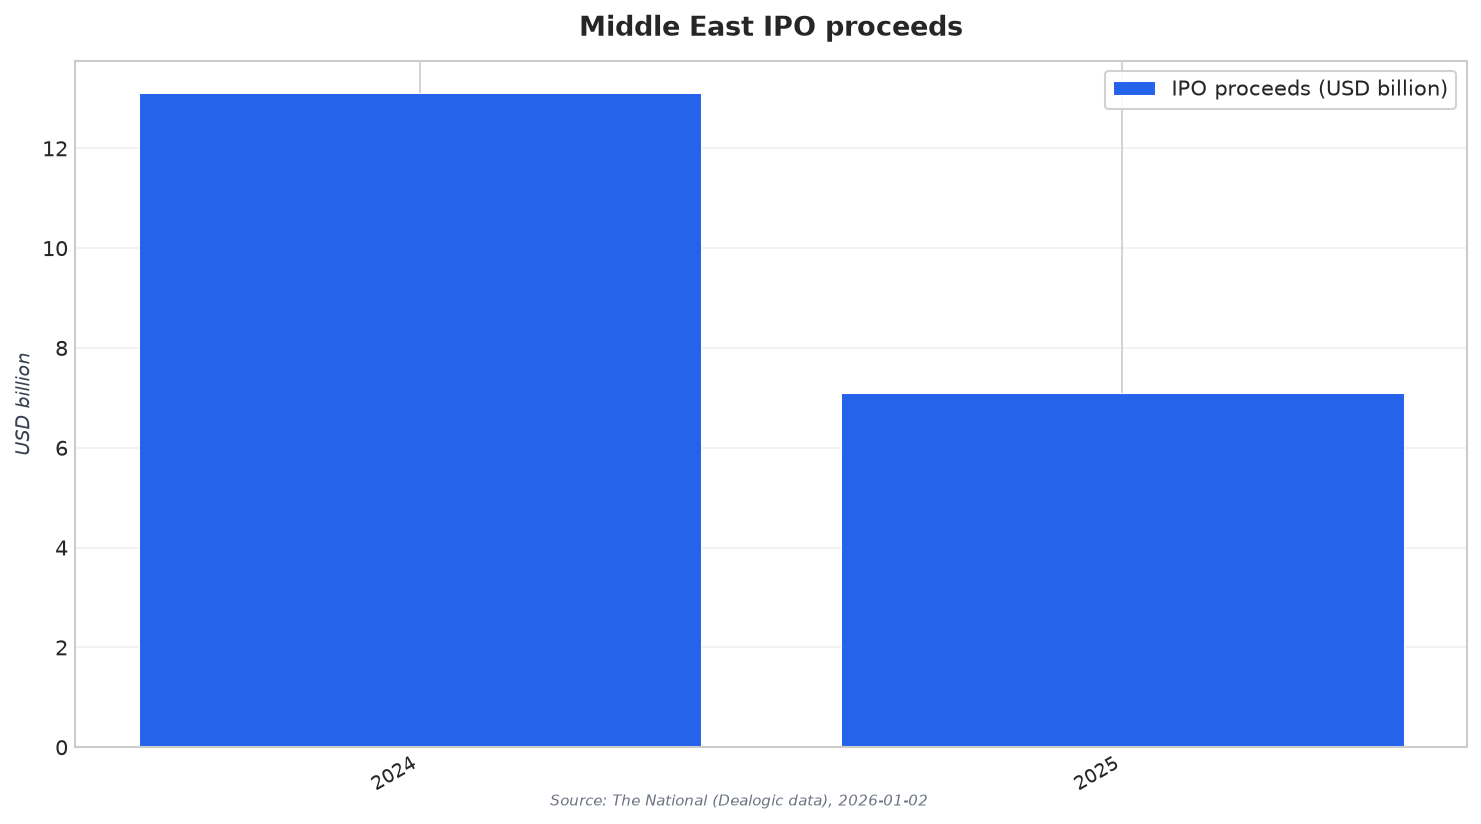
Context from recent years also clarifies why 2026 is being watched so closely. The National said Middle East firms raised $7.1 billion from 61 listings in 2025, compared with $13.1 billion in 2024, and that 2025 was the lowest since 2020 when companies pulled in $2.2 billion, based on Dealogic data. Within the Gulf, it highlighted that UAE companies raised $1.1 billion through three IPOs in 2025, and it named individual deal sizes: Alpha Data raised $163 million, Alec Holdings raised $584 million, and Dubai Residential REIT raised $381 million. In Saudi Arabia, the same report said $4.2 billion was raised through 38 IPOs last year. Together, these figures frame 2026 as a measured recovery phase rather than a simple boom.
Global IPO dynamics are also shaping how the GCC IPO market 2026 is approached, especially around timing and investor attention. EY’s Global IPO Trends Q2 2026 noted that IPO markets are gaining momentum, but execution windows may be episodic and shaped by mega-IPOs and geopolitics. EY also said companies are using more flexible approaches, including IPOs, direct listings, and SPACs, to capitalize on improving conditions. Morgan Stanley, writing about the U.S. market, emphasized that sponsor-backed IPOs often follow extended private ownership that allows companies to build operating scale and strengthen governance before a listing, and it highlighted growing retail participation, including Directed Share Programs. These themes reinforce why Gulf issuers are prioritizing readiness, narrative clarity, and timing discipline as the listing wave develops.
What happened in the GCC IPO market in the first half of 2026?
Which Gulf deals were paused or withdrawn in 2026?
What pipeline listings were cited for the rest of 2026?
How did 2025 fundraising compare with 2024 in the Middle East?
Why are IPO timing windows described as episodic in 2026?