The global nickel market is being pulled in two directions at once: rising long-term demand expectations and near-term surplus pressure. One estimate values the global nickel market at USD 36.4 billion in 2025 and projects a 5.9% CAGR through 2035, reaching about USD 64.3 billion. Another estimate places 2025 at USD 48.74 billion, with a projected rise to USD 92.75 billion by 2034 at a 7.41% CAGR. In both views, Asia Pacific leads, with 57.6% share (USD 20.95 billion) in 2025 in one report and 63.1% share in another. This concentration sets the stage for supply coordination to have outsized effects.
Nickel demand is still dominated by traditional industry. Stainless steel accounts for roughly two-thirds of total demand in 2025, and another source puts it at more than 60% of total consumption, with growth expected to remain sluggish in 2026. Batteries are the second major pillar, but they are also changing: lithium-ion battery demand is cited at approximately 17% in 2025, and another analysis notes a slower pace as non-nickel chemistries, especially LFP, gain share. Against that demand mix, the supply side has been reshaped by Indonesia’s growth and its ability to move material between stainless and battery markets depending on prices and payables.
How Supply Coordination Turns Into Price Power
What makes the Indonesia-Philippines nickel corridor strategically important is how quickly supply policy can move the global balance. One policy adjustment is described as removing an estimated 300,000 tonnes of nickel from global supply, equal to about 10% of global nickel output. The market reaction was measurable: nickel, which had traded well below USD 16,000 per tonne during a downturn, recovered into the USD 18,500 to USD 20,000 per tonne range, briefly approaching USD 20,000 before pulling back. This helps explain why coordinated actions between the two largest nickel ore producers can transmit into benchmarks and downstream battery and stainless supply chains.
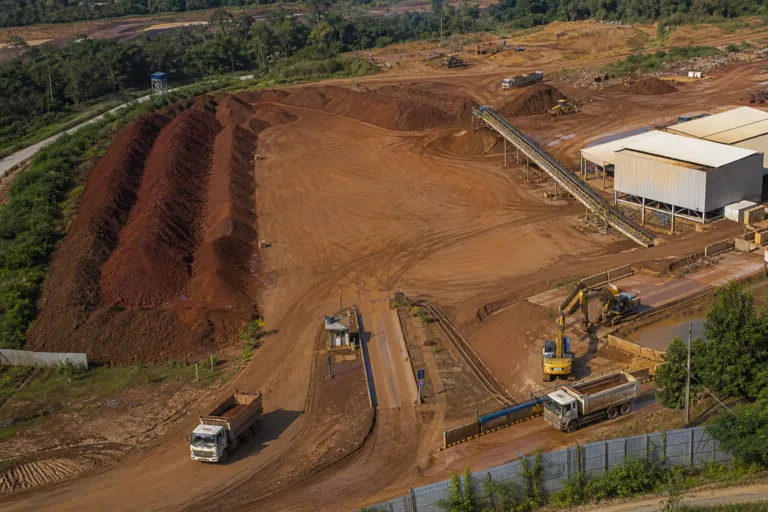
Indonesia’s coordination interest is also operational, not only political. One account notes a structural paradox where domestic smelter capacity has, at times, exceeded the ore volumes Indonesian mining can reliably supply, pushing processors to use Philippine ore as a flexible supplement. Indonesia’s Energy and Mineral Resources Minister Bahlil Lahadalia said Indonesia intends to discuss shipping more ore from the Philippines during periods of domestic supply pressure, structured on a business-to-business basis rather than fixed governmental quotas. The same source flags processing constraints at some HPAL facilities tied to sulphur supply disruptions, tightening battery-grade nickel sulphate output and adding another incentive to secure feed and reagents.
This coordination lands in a market that can still be structurally long. ING Think forecasts a surplus of 209 kt in 2025 and 261 kt in 2026, suggesting continued pressure even as Indonesia pushes for higher-value processing. ING also notes Indonesia’s 2020 ban on raw nickel ore exports to spur processing investment, while warning that approved projects can keep adding capacity and that strict enforcement could tighten supply in the medium to longer term. Meanwhile, USGS figures cited in a market report estimate global nickel mine production at about 9 million metric tons in 2025. In that context, any additional tightening—or smoother cross-border flows—can become a lever that industrial buyers and investors watch closely.
Why does the Indonesia-Philippines nickel corridor matter for battery metals?
What happened to prices when supply was tightened by policy?
Is nickel demand still mostly about stainless steel?
Is the nickel market expected to be in surplus in the near term?
How large is the global nickel market in 2025, according to the sources?